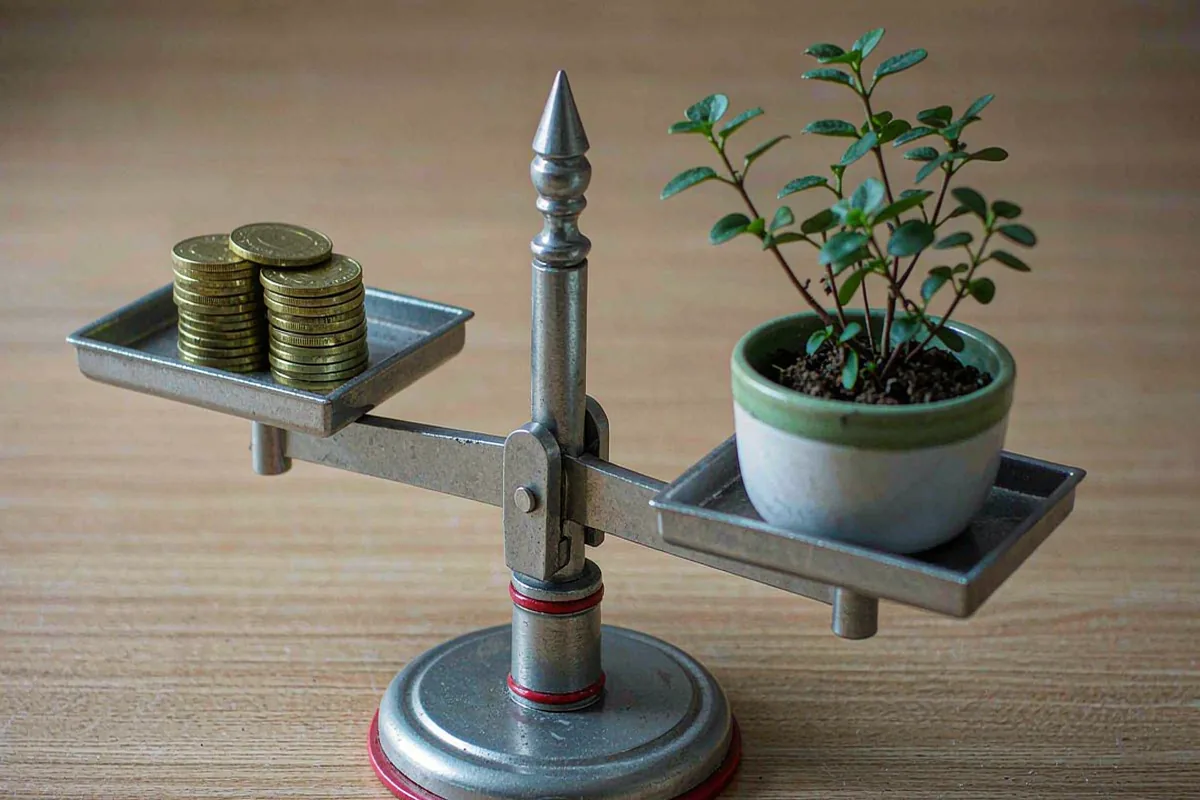
A common mistake is pouring every dollar into the market while keeping no cushion, or hoarding cash and missing growth. The savings-versus-investing balance is the split between money you keep liquid for safety and money you put to work for long-term growth. A simple framework keeps both jobs clear without constant second-guessing.
Cash comes first because it absorbs shocks. An unexpected car repair or job gap is paid from savings, not a sale of investments at a bad time. In most cases, having a liquid reserve prevents forced, mistimed decisions that cost more than any missed return. Treat the cash floor as the foundation; only after it is solid does investing make sense.
A useful mental model is to see savings as insurance and investing as growth. Insurance protects the plan; growth expands it. Skipping the insurance to chase growth often backfires when life interrupts, forcing a sale at the worst moment. Most people sleep better with a real cushion, and better sleep supports steadier long-term decisions.
A widely used guide is to hold three to six months of essential expenses in savings, though your number depends on job stability and dependents. Someone with steady income and no children might sit near three months; a single earner with kids often needs closer to six. Multiply your monthly must-pay bills by that factor to size the cash buffer you should never invest.
Money you will not touch for five years or more can usually be invested, because markets tend to recover over longer windows. A typical approach is to fund retirement and long-term goals from surplus after the cash floor is full. Keep any money tagged for a purchase within roughly three years in savings, since short horizons leave no room to ride out a drop.
Do not wait for the perfect moment to start investing the surplus. Time in the market usually matters more than timing the market, so consistent contributions win for most people. Automate the invest portion the same way you automate savings, sending a fixed amount on each payday. The habit compounds while you focus on work and life.
The split is not fixed. A new job, a baby, or a paid-off mortgage changes both your expenses and your risk. Review the balance every six to twelve months and shift surplus toward whichever side is thin. In most cases a small, steady redirect beats a dramatic overhaul, and it keeps the plan aligned with where you actually are.
Windfalls test the balance most. A bonus or tax refund tempts either hoarding or all-in investing; a planned split handles both. A common rule sweeps part to cash and part to investments based on your current gaps. Decide the split before the money arrives so emotion does not pick the allocation after it lands.
Park the cash buffer in an insured, interest-bearing account so it earns while it waits. A high-yield savings account or money market account typically pays more than checking, though you should confirm current rates with the provider. The investing side belongs in diversified, low-cost vehicles suited to your time horizon. Keep the two clearly separated so neither drifts into the other.
Apply the framework in four steps:
Keep building your plan with these related guides:
Savings strategies vary by person. This article is general information, not financial advice. Rates and rules change; confirm details with the provider and consider your own situation before acting.
Savings strategies vary by person. This article is general information, not financial advice. Rates and rules change; confirm details with the provider and consider your own situation before acting.
